Insurance for expats · Hamburg and online across Germany German insurance, explained and handled in English.
Moving to Germany or already living here? HFH is an independent insurance broker in Hamburg. We compare the whole market and take care of advice, application, policy and claims for you. Every document you get from us is in English.
- 100% of your documentation in English
- Independent broker, whole market
- Free consultation in Hamburg or by video
At a glance
Insurance in Germany for expats: the short answer
- Health insurance is mandatory for everyone who lives in Germany, including long-term care insurance. Without proof of cover, non-EU citizens will not get a visa or residence permit.
- Two systems: public health insurance (GKV) for most employees, private health insurance (PKV) for employees earning above €84,150 a year (2027), the self-employed, freelancers and civil servants.
- Supplementary insurance (dental, hospital, outpatient, travel) tops up public cover where it has gaps.
- Personal liability insurance is not compulsory, but most people in Germany have it and many landlords expect it.
- The usual catch: German insurers write their contracts in German. With HFH you get every document in English and one English-speaking contact for the whole process.
Why HFH
One broker, one language, every policy
We built our expat service around one promise: you never have to deal with German insurance paperwork on your own.
100% English documentation
Advice, comparison, application, policy summary, claims and letters: everything you get from us is in English. Where an insurer only issues the German original, you get our English version alongside it.Independent, whole market
As a broker we work for you, not for an insurer, and compare across the market instead of selling one product shelf.One contact for everything
Health, liability, disability, pensions, real estate and financing: one team in Hamburg for your whole life in Germany.Free for you
Consultation and comparison cost you nothing. We are paid by the insurer only if you take out a policy.
Health insurance in English
Our English guides to health insurance in Germany
Private health insurance (PKV)
Eligibility 2027, costs, pre-existing conditions, family, visa and leaving Germany, explained in plain English.- Anonymous risk pre-assessment
- 100% English documentation
Supplementary health insurance
Dental, hospital, outpatient, travel, sick pay and long-term care top-ups for people with public insurance.- No income threshold
- 100% English documentation
Key numbers 2027
The figures that decide your health insurance options
These values decide whether you may choose private health insurance and how much your employer pays towards it.
- Income threshold for private health insurance
- €84,150
- Income threshold for private health insurance
- Gross per year from which employees may leave public insurance in 2027 (€7,012.50 a month).
- Quelle: Rechengrößen 2027
- Max. employer contribution to private health insurance
- €557.81
- Max. employer contribution to private health insurance
- Per month, at most half of your premium. Plus up to €114.75 for long-term care insurance (outside Saxony).
- Quelle: Calculated from BBG €6,375 and 17.5 %
- Max. public health insurance contribution
- €1,115.63
- Max. public health insurance contribution
- Per month, employee and employer share combined, at the 2.9 % average additional contribution. Long-term care comes on top.
- Quelle: BMG, Zusatzbeitrag 2027
- Age limit for returning to public insurance
- 55
- Age limit for returning to public insurance
- From 55, switching back from private to public insurance is generally no longer possible. Choose carefully.
- Quelle: § 6 SGB V
Compare
Public, private or expat health insurance?
Which option fits depends on your job, income, visa and how long you plan to stay.
| Public (GKV) | Private (PKV) | Expat / incoming insurance | |
|---|---|---|---|
| Who can join | Most employees, students, family members | Employees above €84,150 (2027), self-employed, freelancers, civil servants | New arrivals, usually for a limited period |
| Premium based on | Income (percentage of salary) | Age at entry, health, chosen benefits | Fixed price per plan |
| Family | Spouse and children without own income insured free | Each person pays their own premium | Each person pays their own premium |
| Benefits | Set by law, can change politically | Guaranteed by contract for life | Often basic, check dental and mental health |
| Health check | None | Health questions, pre-existing conditions matter | Varies, often exclusions |
| Visa / residence permit | Accepted | Accepted if it meets German requirements | Check carefully before you rely on it |
| Language | Some funds offer English service | Contracts usually German, with HFH in English | Often English |
Simplified overview. Your individual situation decides; we check it with you for free.
Your checklist
Which insurance do expats need in Germany?
Sorted by priority, from mandatory to useful once you have settled in.
Health insurance
Mandatory from day one. Public, private or temporary expat cover, depending on your status.- Required for visa and work
- Includes long-term care
Dental and supplementary
Public insurance covers dental care only partly. Supplementary plans top up crowns, implants, hospital stays and treatment abroad.- Dental, hospital, outpatient, travel
Personal liability
Covers damage you cause to others. Inexpensive, widely held in Germany and often expected by landlords.- Arrange before you sign a lease
Income protection
Occupational disability insurance (Berufsunfähigkeit) pays a monthly income if you can no longer work in your job.- The earlier, the cheaper
Household contents
Protects your belongings at home against fire, water damage and burglary.- Once your flat is furnished
Legal expenses
Covers lawyer and court costs, for example in disputes with a landlord or employer. Most policies have a waiting period.- Take it out early
Car insurance
Mandatory if you own a car in Germany. We help you transfer your no-claims history where insurers accept it.- Required for registration
Pension and savings
Private and company pension plans, with a view on what happens if you leave Germany again.- Portable solutions
More than insurance
Settling in Hamburg? We help with the rest, too
HFH Group combines insurance, real estate, financing and investments under one roof.
How it works
Insured in four steps, all in English
Tell us about you
Job, income, visa status, family and how long you plan to stay. Existing policies from home are welcome.Get your comparison
You receive a clear English comparison of suitable options, including what we would not recommend and why.Decide together
In Hamburg or by video we go through benefits, health questions and costs. For private health insurance we check pre-existing conditions anonymously with several insurers first.Application and aftercare
We prepare the application, translate every document and stay your English-speaking contact for claims, premium changes and life events.
Your contact
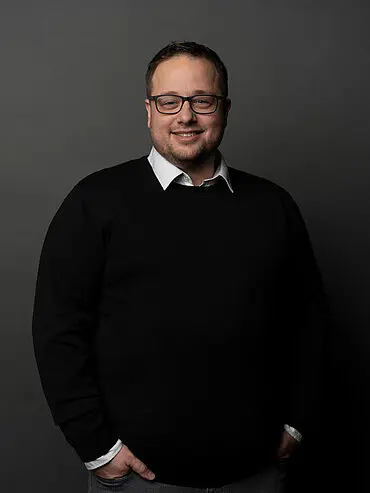
Florian Kellmann advises you in English
Florian Kellmann is a broker in the HFH team and looks after you from the first comparison to ongoing support. Meet us at our office in Hamburg or by video from anywhere in Germany.
HFH Hamburger Finanzhaus GmbH, Willy-Brandt-Straße 67, 20457 Hamburg
f.kellmann@hfh.de · +49 40 4143790
FAQ
Frequently asked questions about insurance for expats in Germany
Is health insurance mandatory for expats in Germany?
Yes. Everyone who lives in Germany must have health insurance, including long-term care insurance. Non-EU citizens need proof of adequate cover for their visa and residence permit, and employers need it before your first working day.
Can I get private health insurance in Germany as an expat?
Yes, if you are an employee earning more than €84,150 gross a year (2027), self-employed, a freelancer or a civil servant. Your nationality does not matter. Premiums depend on your age at entry, your health and the benefits you choose, not on your income. More in our guide to private health insurance.
Can my whole insurance process be handled in English?
Yes. With HFH, consultation, comparison, application, policy explanation, claims and all correspondence are in English. Most German insurers issue their legally binding contract in German. In that case you get our English version of every document alongside the original, and we tell you which insurers offer English documents themselves.
Is private or public health insurance better for expats?
It depends. Private insurance is often cheaper and offers more for young, healthy people without dependants. Public insurance covers your spouse and children without own income at no extra cost and is usually better for families on one income. If you might return to Germany's public system later, plan carefully: after 55 that is generally no longer possible.
What is expat or incoming health insurance?
Temporary private cover for new arrivals, typically for a few years. It can be a bridge until you qualify for public or full private insurance. Benefits are often more limited, for example for dental care, pregnancy or mental health, and not every policy is accepted for every residence permit. We check this before you rely on it.
What is supplementary health insurance?
Private add-on plans for people with public insurance. The most common are dental insurance, hospital insurance (private or semi-private room, chief physician), outpatient plans (glasses, alternative medicine) and travel health insurance. You keep your public insurance and close the gaps. More in our guide to supplementary health insurance.
Does public health insurance cover the dentist?
Only partly. Public insurance pays a fixed subsidy for standard dental care. For crowns, implants, inlays or professional cleaning you can quickly pay several hundred to several thousand euros yourself. Supplementary dental insurance covers much of that difference.
How much does my employer pay towards private health insurance?
Your employer pays half of your premium, in 2027 up to €557.81 a month for health insurance and up to €114.75 for long-term care insurance (€82.88 in Saxony).
Can I keep my health insurance from my home country?
Sometimes. EU citizens can use the European Health Insurance Card for temporary stays. If you live and work in Germany, you generally need German or German-compliant cover. International policies are only accepted if they meet German requirements. We check your existing policy for free.
Do I need liability insurance in Germany?
It is not legally required, but strongly recommended and cheap. It pays if you damage someone else's property or injure someone, which can otherwise cost you a lot of money. Many landlords expect it.
What happens to my insurance if I leave Germany?
Health insurance can usually be ended when you move abroad permanently. Private insurers can offer to keep your contract or part of it, which can make a later return easier. Pensions and disability insurance often continue. Talk to us before you move, so you don't lose anything.
Does the consultation cost anything?
No. Consultation and comparison are free and without obligation. As a broker we are paid by the insurer only if you take out a policy.
Get started
Book your free consultation in English
Tell us briefly about your situation. We will reply in English with a first assessment and suggest a time for a call or video meeting. Free and without obligation.
Your contact: Florian Kellmann, f.kellmann@hfh.de
Thank you for your enquiry. We will get back to you as soon as possible.
As of November 2026. Values for 2027 are based on the Social Insurance Calculation Values Ordinance 2027 adopted by the Federal Cabinet (Federal Council approval pending) and the average additional contribution rate of 2.9 % set by the Federal Ministry of Health on 30 October 2026.
HFH Hamburger Finanzhaus GmbH acts as an insurance broker. The terms of the respective insurance contract apply; where an insurer designates the German version as legally binding, that version prevails. German pages: Versicherungen · Krankenversicherung